
The short answer: A property purchase built to run for twenty years should not be decided by a news cycle. Many newer investors have never held through a multi-year decline, so rate rises and policy headlines can read as proof the market is breaking. Before reacting, ask whether something structural has changed, such as your serviceability or the fundamentals of where you bought, or only the coverage.
A twenty year decision is being made off a headline
If you have never held a property through a decline that took years to reverse, your risk tolerance has never actually been tested. It's an assumption you're carrying, not something you know about yourself. That gap is shaping a lot of choices right now.
Buyers who came through the 2017 to 2019 correction across Sydney and Melbourne already sat this test once. Prices fell, stayed down, and took years to recover in some pockets. They found out under real conditions what they could stomach.
Buyers who started after that mostly know a different market. Low rates, easy credit, quick recoveries whenever prices dipped. That's simply the environment they learned in, and it means their tolerance for a real downturn has never had to hold under pressure.
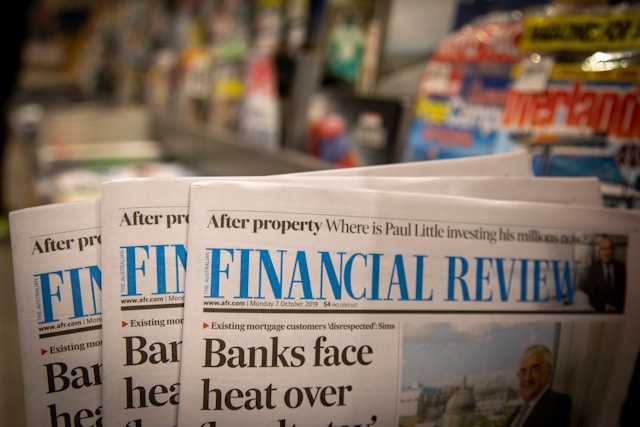
That gap changes how the current coverage lands. Without a prior down-cycle to measure against, three rate rises or a shift in tax policy doesn't read as a normal part of a longer cycle. It reads as proof the whole thing is breaking. Makes sense, given what these buyers have to go on. But it means the decision on the table isn't really a response to the market. It's a response to how the market is being written about.
Worth being precise here. In January 1990, the cash rate sat at 17.5 per cent. Two years later it had been cut by more than half. That's a fact about 1990. It isn't a prediction about now, since every cycle has its own causes and runs its own length. What the 1990 example actually shows is that the commentary at the time didn't describe what happened next.
The mistake is letting a media cycle make a decision that was built to run for twenty years. A rate rise or a run of alarming headlines is real. It's also short-lived next to the timeframe the purchase was built for.
Selling or delaying a purchase locks in whatever position you're in today and gives up any chance of benefiting from wherever the cycle goes next. Holding only works if your position was genuinely serviceable to start with, not just comfortable while rates happened to be low. Neither path is free. The question is which cost you can actually absorb.
Reading this as "ignore the news and it'll come good" would be its own mistake. Plenty of buyers in 1990 were overextended and didn't come out the other side, whatever they read or ignored. Serviceability, worked out before the cycle turns, is what decides whether tuning out the noise is even an option for you.
Before reacting to any rate move or policy headline, ask one question: is this about the market, or about the coverage of the market? A rate cycle or a piece of legislation is usually temporary next to the length of the decision you made. Your serviceability and the fundamentals of where you bought are structural, and neither shows up in a headline. If it's the coverage unsettling you, that's noise for the decision in front of you. If something structural has actually changed, that's worth a proper conversation with your broker or planner, not a reaction to this week's news.
Frequently asked questions
Should I sell or delay buying because of rate rises or bad headlines?
Only if something structural has changed. Selling or delaying locks in today's position and gives up the next stage of the cycle, so check whether it is the market or the coverage of the market that is unsettling you.
Does ignoring the news mean my property will come good?
No. Holding only works if your position was genuinely serviceable to begin with. Investors who were overextended in 1990 did not come out the other side, whatever they read.
What does the 1990 interest rate cycle show investors?
The cash rate was 17.5 per cent in January 1990 and was cut by more than half within two years. It is not a prediction, but it shows commentary at the time did not describe what came next.
Disclaimer: The information in this article is general in nature and does not take into account your personal objectives, financial situation, or needs. It is not financial, legal, or tax advice. The Nelis Group accepts no liability for actions taken based on this content. You should seek independent advice from a relevant licensed professional before making any decisions and always confirm the latest rules and thresholds with your state revenue office or relevant authority.
Short emails every Sunday and Thursday on what's moving in the market and how I'm thinking about it. Structured thinking, no hype.
Unsubscribe any time.