The short answer: Plan a property purchase on your reliable income, what you'd earn if you weren't re-signed tomorrow, and stress test it on your worst realistic 12 months. Treat your best contract year as a bonus that speeds up the plan. Lenders may count only part of your playing income, so start with a broker who understands it.
It isn't a bad property that hurts athletes
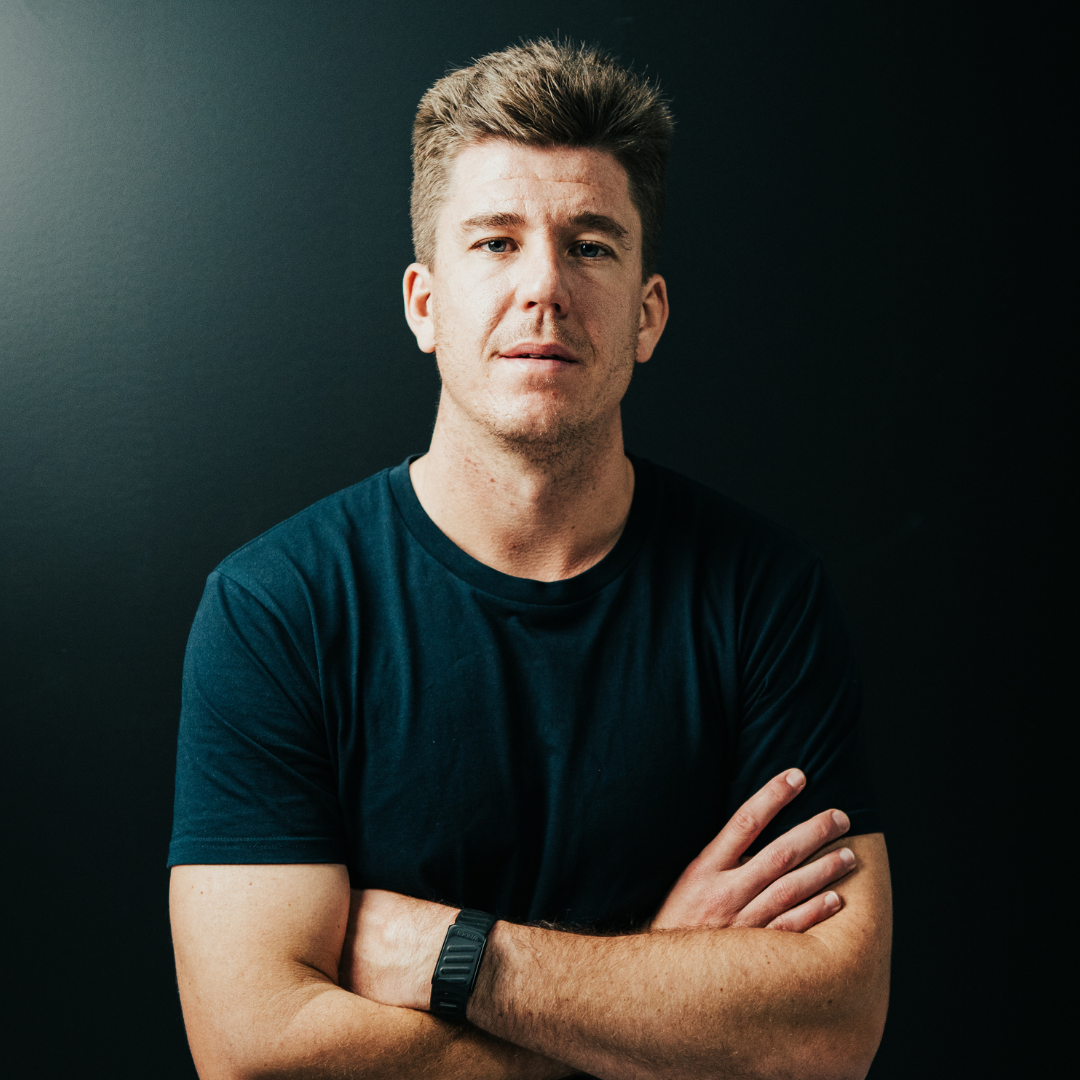
I'm a buyers agent, and I played 200 games for the Aspley Hornets between 2009 and 2023, across the NEAFL, VFL and QAFL. I never played AFL. I played the level below it, with a day job and match payments that rose and fell with selection.
What hurts athletes in property usually isn't a bad property. It is a good property they can't hold once the contract changes.
Most financial planning assumes income rises steadily for 40 years. An athlete's doesn't. The playing years are often the shortest, highest earning stretch of a working life, and they have an end date nobody can see.
Write down three incomes before you look at a listing
- Peak income. What you earn in a good contract year, including match payments and bonuses.
- Reliable income. What you'd earn if you weren't re-signed tomorrow: your day job, a post-footy role or a realistic starting salary.
- Floor income. The worst realistic 12 months: injured, between contracts or between careers.
Plan around number two. Stress test against number three. Number one speeds up the plan. It isn't the plan.
The trade-off is that you'll buy less, or later, than your best year suggests you could. In return, an injury or a delisting is a setback, not a forced sale.
How lenders look at athlete income
Lenders treat sporting income differently. Some count only part of your playing income or want two years of history, and state league match payments may not count at all.
That makes the broker the first call, not the last (how to increase borrowing capacity covers what lenders look at). Look for one who understands athlete income, and plan on day job income first. Structure and tax, including how negative gearing and capital gains tax rules apply to you, sit with your accountant.
Time each purchase to your career stage
- Rookie and early years. Income is a low base, sometimes with a second job. The risk: you can't borrow much, so the temptation is to wait.
- Established or peak contract. The highest you may ever earn. The risk: buying a structure that only works on peak income.
- Contract gaps, injury, delisting. Income can drop sharply with little notice. The risk: being forced to sell at the wrong time.
- Transition. Income resets to a new career, often at entry level. The risk: holding costs that suited you at 26 don't suit you at 32.
The biggest mistake I see is buying at peak earnings into a structure that only works while the contract lasts.
My first property, in Kallangur in 2014, didn't have a job. Nobody asked what it was meant to do next, including me. My manager at AFL SportsReady was the first person to show me that equity in one property could fund the next deposit, and that conversation changed the direction of my life. The years before it were the most expensive question I never asked.
A job for each property makes the order work. For example: "This one is for long-term growth; I'll hold it for 10 years and use its equity for the next purchase after I've transitioned." Or: "This one is for cash flow, to carry me through the first two years after footy."
Build the buffer, then run the contract test
Hold 6, 9 or 12 months of repayments and holding costs in cash before you make an offer: 6 if you're aggressive, 9 if you're moderate, 12 if you're conservative. Size it across everything you own plus the next purchase, with no rent counted. The free Buffer Calculator works it out.
For an athlete, the buffer is what stops an injury, a delisting or a contract gap from forcing a sale. It also stops a big year turning into a bigger lifestyle instead of a bigger base.
Before every purchase, add one question to the usual checks on strategy, cash flow and capital:
If you weren't re-signed tomorrow, could you cover the property's net monthly cost on your reliable income, and hold through a floor income year?
If the answer is no, the structure is too tight for your career stage. Look at a lower price point, or wait until your post-footy income is clearer.
The free Holding Power Check works out a property's net monthly cost at your full pre-approval, so you can test it against your reliable income.
Beware the near win
Footy taught me that plans rarely fall apart when things go badly. They fall apart when success feels close. Your equity jumps, you have a big year, or a teammate's suburb has run. None of those changes your plan's inputs. They are feelings about how close you are.
Review your portfolio the way you review game footage: on a schedule, not on a feeling.
Your team matters more than any one property
You have a coach, a physio and a manager because no one person can do every job. Property is the same: a broker who understands athlete income, an accountant, your manager, your club or player association's transition staff and, if you want one, a buyers agent to search, price and negotiate while you train.
The decision rule: buy only what your reliable income can hold, with the buffer in place, and let the peak years speed the plan rather than set it. Our buyers agent for athletes page shows how we plan around uneven income. What is your reliable income, if you weren't re-signed tomorrow?
Frequently asked questions
Can athletes get a home loan on contract income?
Often, but lenders treat sporting income differently. Some count only part of playing income or want two years of history, and state league match payments may not count. Start with a broker who understands athlete income.
What income should athletes plan a property purchase on?
Your reliable income: what you'd earn if you weren't re-signed tomorrow. Stress test it against your worst realistic 12 months, and treat your best contract year as a bonus.
How big a buffer should an athlete hold before buying property?
Six, nine or twelve months of repayments and holding costs across everything you own plus the next purchase, with no rent counted, held before you make an offer.
Disclaimer: The information in this article is general in nature and does not take into account your personal objectives, financial situation, or needs. It is not financial, legal, or tax advice. The Nelis Group accepts no liability for actions taken based on this content. You should seek independent advice from a relevant licensed professional before making any decisions and always confirm the latest rules and thresholds with your state revenue office or relevant authority.
Start with the decision rules I use, in the order you'll face them. Then short emails on how I buy, what I hold and when I walk away.
Unsubscribe any time.